

EarnIn: Why Wait for Payday?
by Activehours Inc.
4.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.8
- Price
- Free
- Download
- 10.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
 Analysis by Getfullapps
When an unexpected expense lands before payday, the problem is often timing rather than income. That is the situation EarnIn is built around: it is a finance app from Activehours Inc. that lets eligible users access part of their earned pay early instead of waiting for the regular payroll date. After spending time with it, my view is straightforward: it can be a useful short-term bridge, but it works best when treated as a controlled cash-flow tool rather than as extra money.
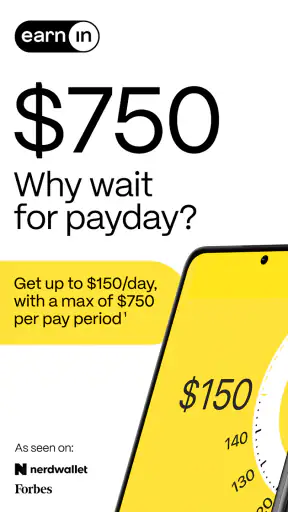
The app is free to install and is rated for Everyone, which makes the basic proposition easy to understand. Its store summary describes early payday access of up to $150 in a day, with a maximum of $1,000 during a pay period. Those limits are important because they frame EarnIn as a way to smooth a temporary gap, not as a replacement for a full paycheck or a long-term borrowing solution.
How EarnIn feels in everyday use
The most convincing use case is a very ordinary one. Imagine that a utility bill, prescription, or necessary car repair arrives several days before wages are deposited. A traditional credit card may solve the immediate problem, but it can also turn a small timing issue into a balance that follows you for months. EarnIn takes a different approach by connecting the request to money you have already earned. That distinction is the reason I find the app more interesting than a generic cash-advance service.
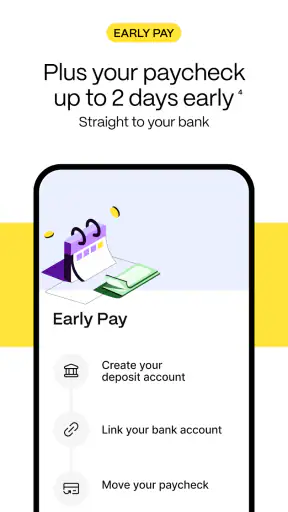
The practical workflow begins with setting up the app and establishing the information it needs to determine eligibility. From there, the important question is not simply “How much can I get?” but “How much can I safely move forward without making the next payday uncomfortable?” I would use the smallest amount needed, even if the available limit is higher. That habit is more valuable than chasing the maximum because the next deposit still has to cover normal bills, food, transport, and any automatic payments.
One subtle strength is that the app encourages a different mental model from ordinary borrowing. A credit card gives you spending power that may remain outstanding for an uncertain period. An earned-wage advance is tied to money connected with work already completed. That does not make it free money, and it does not remove the need to repay the advance, but it can make the purpose clearer: cover a short gap, then return to the normal pay cycle.
I also think the daily and pay-period boundaries are useful guardrails. They force the user to think in terms of a limited amount rather than an open-ended line of credit. If you are tempted to use every available dollar because it is visible in the app, those limits provide at least some friction. In personal finance, a little friction can be helpful when the alternative is making an emotional decision during an expensive week.
The strongest reason to choose it
EarnIn’s main advantage is timing. For someone whose income is regular but whose bills do not line up neatly with payday, earlier access may prevent a late payment, an overdraft, or the need to ask friends and family for help. It is particularly relevant for workers who already know when their wages are earned but cannot access them until the employer’s scheduled payroll process finishes.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
That makes it different from a conventional personal loan. A loan is usually designed around a larger amount and a repayment schedule that extends beyond the immediate pay cycle. EarnIn is more narrowly focused on the space between work being completed and wages arriving. If your need is genuinely temporary, that narrower design can be a better match than borrowing more than necessary.
It is also more direct than relying on a credit card for every emergency. With a card, the purchase and the repayment can become psychologically separated. You may remember the original repair or grocery trip, but the balance can remain in the background long after the event. EarnIn keeps the connection to the coming paycheck visible, which can make the cost of the decision easier to understand.
Still, I would not describe the app as a substitute for an emergency fund. An emergency fund gives you money that is already yours and does not reduce the next paycheck. EarnIn helps with access, not with building a cushion. The best long-term use is to handle a rare mismatch while working toward savings that can eventually make advances unnecessary.
Where the experience needs caution
The biggest weakness is also the central trade-off: receiving money early means having less flexibility when payday arrives. If the original expense was part of a wider pattern of being short every pay period, an advance can make the following week harder. The app may solve today’s problem while leaving the underlying budget unchanged. I would be especially careful if rent, debt payments, or other fixed expenses already consume most of the next deposit.
Another point that deserves attention is the difference between a free app and a cost-free financial decision. The app itself is free, but moving money early can involve choices or charges that a user should review carefully before confirming a request. I would never tap through the final step without checking the amount arriving, the amount expected later, and any optional service presented during the process. A convenient interface should not replace reading the transaction details.
Speed can create its own risk. When money appears available in a few taps, it is easy to treat an advance like ordinary spending money. My practical rule would be to open EarnIn only for a named expense. “I need this amount for the electricity bill” is a safer reason than “I might as well take what is available.” That small change turns the app from a temptation into a budgeting instrument.
Eligibility and access can also depend on the user’s work and pay situation. The app is not equally suitable for every type of income. Someone with irregular earnings, unpredictable pay dates, or a complicated employment arrangement may find the experience less useful than a person with a stable payroll rhythm. Before relying on it for a deadline, I would complete setup early and understand how the app handles my particular work pattern.
Three smarter ways to use the app
First, I would use EarnIn as a “bridge budget,” not as a second account. Before requesting money, I would write down the exact bill, its due date, and the next payday. Then I would subtract the advance from the expected deposit in my normal budget. This prevents the common mistake of planning with the full paycheck and forgetting that part of it has already been moved forward.
Second, I would reserve it for expenses where timing has a clear consequence. A necessary prescription, a basic household bill, or an urgent transport need has a stronger case than discretionary shopping. This is a non-obvious advantage of the app’s design: because the amount is limited, it can support prioritization. The limit becomes a reminder to distinguish a real cash-flow emergency from a purchase that can wait.
Third, I would watch for repetition. One advance after an unusual expense is very different from requesting one every pay cycle. If I found myself using EarnIn on a predictable schedule, I would stop and rebuild the budget around the next deposit. At that point, a conversation with an employer about pay timing, a conventional savings plan, or a lower-cost banking option might be more appropriate. Repeated advances signal a structural shortfall, not merely bad timing.
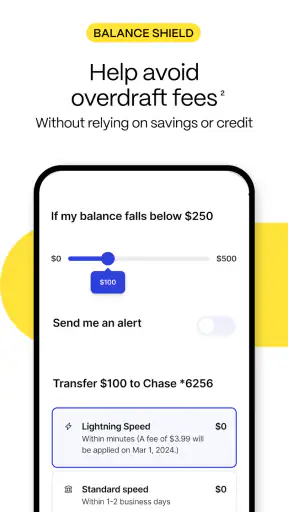
There is also a useful comparison with overdraft protection. Overdraft tools react after an account falls short, while EarnIn is intended to make funds available before that shortage occurs. That proactive approach may feel more controlled, but it requires the user to forecast correctly. If you are unsure about upcoming automatic withdrawals, moving money early may not prevent trouble; it could simply change when the account becomes tight.
Who will get the most from it
I would recommend EarnIn first to a worker with dependable income, a clear pay schedule, and a one-off expense that arrives before wages. That person can calculate the effect on the next paycheck and use the app without pretending the advance increases total income. The app is also a reasonable option for someone who wants a smaller, purpose-specific alternative to carrying an unexpected expense on a credit card.
It may suit people who value a simple, mobile way to manage a narrow cash-flow problem. The finance category can be intimidating when every option looks like a formal loan application. EarnIn’s appeal is that its central idea is easy to grasp: access a portion of pay connected to work already done, then return to the ordinary pay cycle.
I would tell a friend to skip it, or at least compare other options first, if the requested amount is for recurring groceries, rent, or debt payments. Those needs do not disappear after payday, so an advance can become a repeating patch. Someone with a growing credit balance should also avoid adding another short-term obligation without first mapping the full month’s expenses.
It is not the best choice for a person who needs a large sum, a long repayment period, or predictable financing over several months. A traditional personal loan, a negotiated payment plan, or assistance from a local service may fit those situations better. EarnIn’s value comes from its narrow purpose, and that same narrowness is a limitation when the financial problem is bigger than a pay-date mismatch.
What the app’s track record tells me
EarnIn has been available since January 21, 2014, and its current version is 16.53. It supports Android 8.0 and later, so users on older devices should check compatibility before planning around it. The app has passed the ten-million-install mark and holds an average rating of 4.8 from around 300 thousand ratings, with roughly 140 thousand written reviews. Those figures suggest that the basic concept has found a large audience, although popularity does not remove the need to examine each transaction carefully.
The developer, Activehours Inc., has kept the product focused on early access to earned pay rather than presenting it as a broad financial-management suite. I like that focus because it makes the app easier to judge. You do not need to ask whether it replaces every banking tool; you need to ask whether it solves your specific timing problem without creating a worse one after payday.
The Everyone content rating is consistent with the app’s straightforward financial purpose, but younger users should still involve a responsible adult when making decisions about income and repayment. A simple interface can make a financial commitment look harmless. The right question is always whether the next paycheck remains sufficient after the advance and any related cost are accounted for.
My final recommendation
After reviewing EarnIn as a finance app, I see it as a useful emergency bridge with a clear boundary. Its best feature is not merely the ability to receive money early; it is the way that early access can match a short-term need to wages already earned. That can be genuinely helpful when a bill is due at the wrong time and the alternative is a costly overdraft or revolving card balance.
My reservation is equally clear: the app cannot repair a budget that is short every month. If you use it with a specific amount, a specific expense, and a realistic plan for the next payday, it can be sensible. If you use it because there is never enough money until the next deposit, it risks becoming part of the cycle rather than an escape from it.
My verdict: EarnIn is worth considering for stable earners facing an occasional gap between work and payday, especially when a smaller advance is enough to protect an essential payment. I would not make it my default spending source, and I would compare the final terms with a credit union, employer option, or other lower-cost alternative whenever time allows. Used deliberately, it is practical; used automatically, it can make tomorrow’s budget tighter.
Pros
- Instant access to earned wages.
- Simple and user-friendly interface.
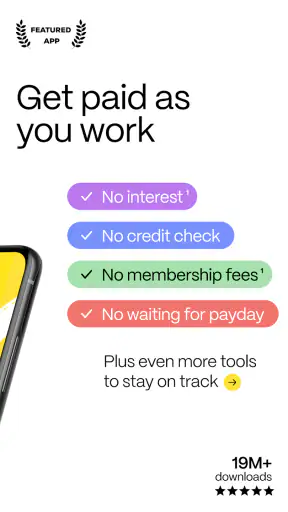
- No interest or hidden fees.
- Connects easily with your bank.
- Helps manage financial emergencies.
Cons
- Requires access to banking info.
- Limited to eligible employers.
- Not a full payroll replacement.
- Daily limits on withdrawals.
- May encourage poor budgeting.
FAQs for EarnIn: Why Wait for Payday?
What is EarnIn and how does it work?
EarnIn is a financial app that allows users to access their earned wages before payday. By connecting to your bank account and tracking your hours worked, EarnIn enables you to withdraw up to $100 per day. The app deducts the amount you’ve withdrawn on your next payday, with no interest or mandatory fees.
Is EarnIn safe to use?
Yes, EarnIn is considered safe. The app uses bank-level encryption to protect your data and does not store sensitive information on your device. It requires access to your bank account to track your direct deposits, ensuring funds are available for withdrawal. Always use strong passwords and monitor your accounts regularly.
Are there any fees associated with EarnIn?
EarnIn does not charge mandatory fees or interest. Instead, it operates on a tip-based system, where users can choose to tip an amount they feel is fair for the service. This means you can access your earned wages without incurring additional costs, but tips help support the app’s operations.
How quickly can I access my funds with EarnIn?
Funds are usually available within one business day. However, for faster access, EarnIn offers a feature called Lightning Speed, which allows for almost instant transfers. To use this feature, your bank must support it, and there may be additional eligibility requirements to meet.
What are the eligibility requirements for using EarnIn?
To use EarnIn, you must have a steady paycheck with direct deposit, a checking account, and a fixed work location or electronic timesheet. The app also requires you to have a regular pay schedule. These criteria help EarnIn verify earnings and ensure that withdrawals are made against actual earned wages.

EarnIn: Why Wait for Payday?
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@earnin.com, visit https://www.earnin.com, or review their https://www.earnin.com/privacy.










